The Guarantee Product What is it? There are 3 parties in the Credit Guarantee Program:
- The Borrower - the SME / entrepreneur
- The Lender – the financial institution
- The Guarantor – the agency
How does this operate?
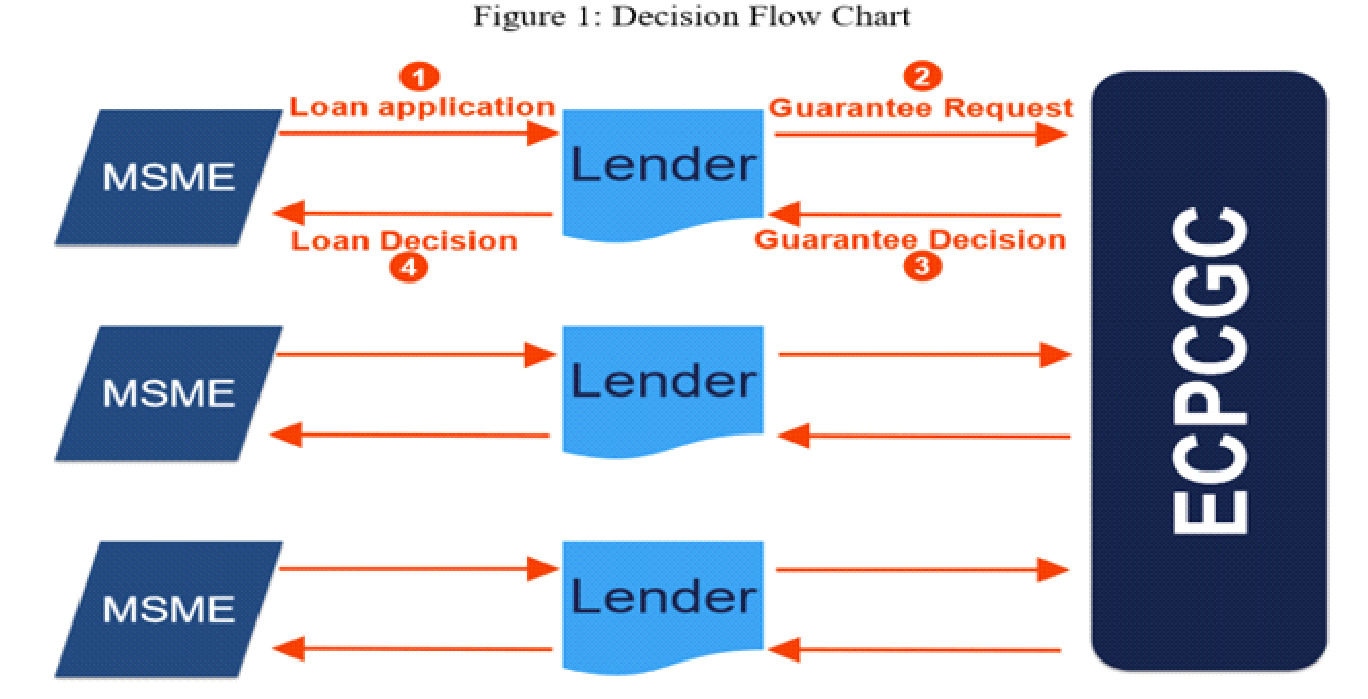
- Owners of MSMEs will apply to their local lender for a loan.
- If the lender is not able to approve the application using the MSME’s conventional credit standards, it may decide to request a guarantee.
- The ECPCGC team will review the application and determine if a guarantee is appropriate.
- The target customer is a business owner who has adequate cash flow to make the loan payments but may not have adequate assets to pledge as collateral, presents more risk than usual or is in an area of business that is relatively new for the lender—such as the creative industries or medical services.
- The lender will collect payments directly from the borrower and will be responsible for liquidating collateral in the event of a default.
- A guarantee fee of 1.5% per annum will be charged on the guaranteed amount, calculated on a reducing balance basis (for overdrafts, the fee is charged each year on the full guaranteed amount). The proceeds are used to help offset any losses absorbed by the Corporation.
Our Guarantee Products
We offer a suite of five guarantee products designed to fit the differing needs of entrepreneurs:
- Classic Guarantee – up to 75% cover on loans up to $750,000
- Working Capital Guarantee – up to 80% cover on loans up to $200,000
- Start-Up Guarantee – up to 80% cover on loans up to $100,000 for businesses operating 3 months to 2 years
- MSME Growth Guarantee – up to 80% cover on loans up to $50,000, no equity required
- TaiwanICDF Women’s Guarantee – up to 85% cover on loans up to $40,000 for women-owned businesses
All amounts are in Eastern Caribbean Dollars (XCD).